Learn With Jermaine—Subscribe Now!
I share what I learn each day about entrepreneurship—from a biography or my own experience. Always a 2-min read or less.
Posts on
Investing
Trump Accounts Just Got $6.25 Billion More Interesting
Earlier this week, I posted about Trump accounts potentially reshaping the stock market (see here). I used Michael Dell’s $6.25 billion donation to Trump accounts as an example of how direct stock ownership could be passed to tens of millions of Americans. However, it now appears that Dell is taking a different approach.
Yesterday (10/8/26), Dell announced that on Friday, 10/9/26, 25 million children will have $250 deposited into their Trump accounts in fulfillment of his donation promise. See his post on X announcing it here and below:
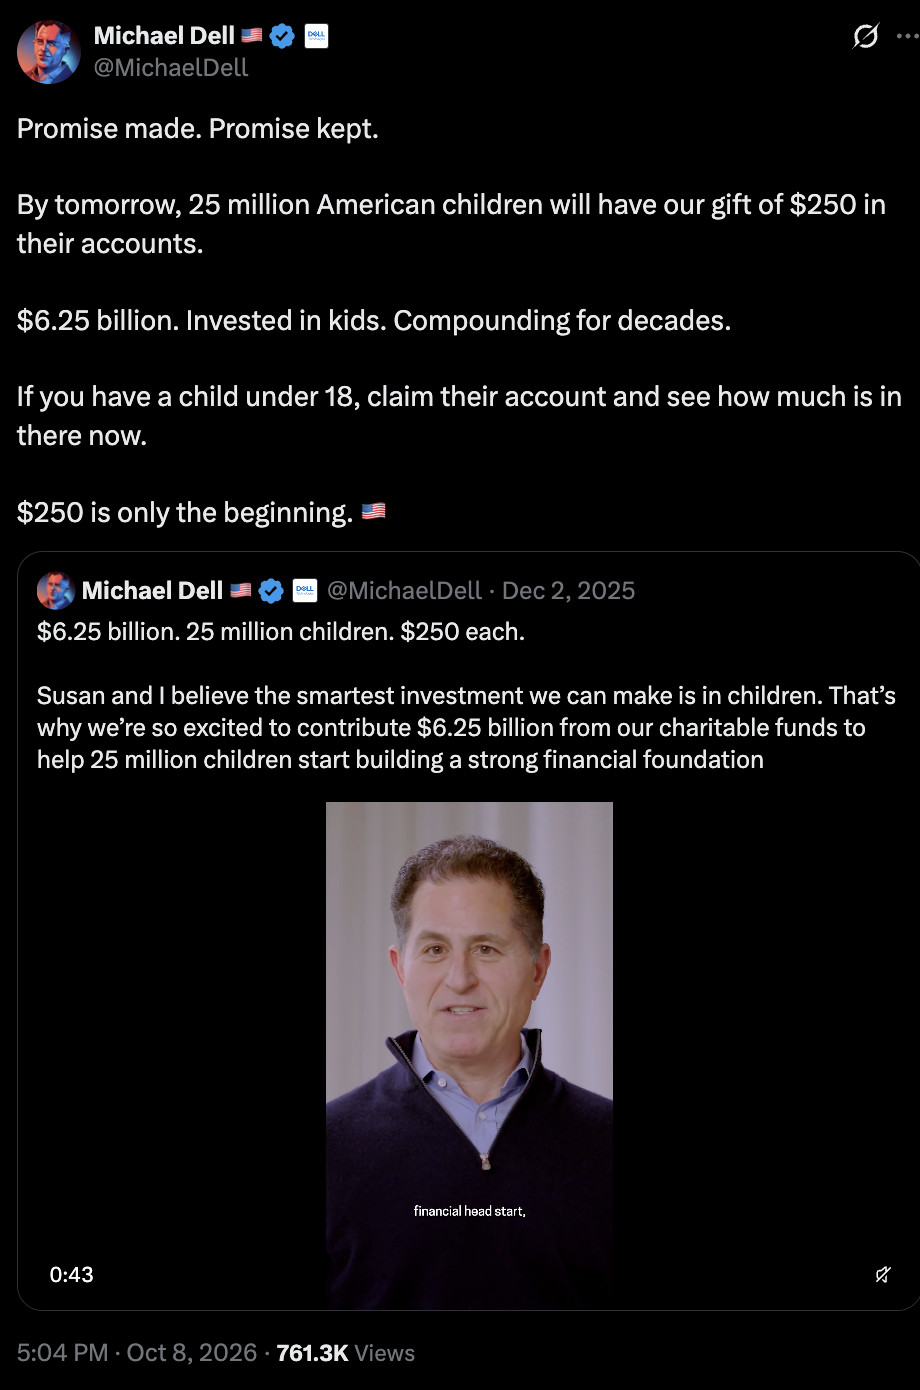
It looks like this is a cash contribution to the accounts, not a stock contribution.
The rollout of Trump accounts is moving fast. This $6.25 billion donation is evidence of that, and I imagine others will donate to Trump accounts. We’ve never seen anything like this before. I’m curious about how this rollout will go and what the long-term impacts on the stock market will be.
Could Trump Accounts Reshape the Stock Market?
Last week, the Treasury Department announced that it will automatically enroll more than 60 million children under 18 in the government’s Trump accounts. The speed with which it is acting on this initiative speaks volumes about its priority. The government announced the accounts in June. The idea behind them is for children to build wealth by being invested in the U.S. stock market at an early age. Any child born between 2025 and 2028, inclusive, will receive a contribution of $1,000 from the government if the child’s parent or guardian elects this option while setting up the account. Accounts have a $5,000 annual contribution limit, and contributions can be made via payroll deductions (i.e., Mom and Dad can have it come out of their paycheck).
The law says the fund’s administrators must invest cash contributed to these accounts in index funds, but that doesn’t apply to stock donations: It will be legal for someone to donate an individual stock to a minor via their Trump account (the minor or their parents just can’t sell the stock for five years).
Michael Dell committed to donating over $6 billion to Trump accounts a few months back. In theory, he could gift $6 billion in Dell stock to Trump accounts, and that would be within the rules. Said differently, Dell (or any other wealthy person, for that matter) could instantly make millions (or tens of millions) of children shareholders in a single company.
I don’t think anything like this has ever existed before, and Trump accounts seem like a big deal. As far as I know, this is the first time that the ability to give ownership in a single public company (free of charge) to a large percentage of the population, and restrict their ability to sell, has existed.
I need to noodle on this more, but based on my reading about the history of the stock market and ETFs, this feels like something that could transform the U.S. stock market.
The Price of Sentiment
One thing I’ve been thinking about this year is how much narrative and sentiment impact company valuations. I tend to be fact oriented, so paying attention to narrative doesn’t come naturally to me. But over the years, as a private-market investor in venture capital and a public-equity-market investor, I’ve been forced to acknowledge the impact of narrative and sentiment. This year’s AI-related sentiment has greatly impacted private and public valuations and led to some massive acquisition prices.
The quote that’s helped me incorporate sentiment and narrative into my thinking is from Benjamin Graham: “In the short run, the market is a voting machine but in the long run, it is a weighing machine.” He’s talking about the public stock market, but this holds true for public and private equity markets.
When sentiment and narrative are elevated, what people think about a company has an outsize impact on what they’ll pay to own a piece of it. But this valuation approach tends to be relatively short-lived. When sentiment is strongest (positively or negatively), jaw-dropping transactions that are anchored in sentiment and narrative more than in numbers sometimes occur. But as time passes and sentiment normalizes, buyers and acquirers tend to value companies based on the underlying business fundamentals.
This year has been interesting, and it’s enhanced my understanding of how big an impact sentiment can have on the prices people are willing to pay to own some or all of a company.
Great Investors Position for Change Before It Arrives
Last month I read How to Get Rich in American History by Joseph S. Moore. It’s a history book that outlines the strategies Americans used to create wealth and climb the economic ladder over 300 years. Chapter 2, “Fast Time, Slow Time,” described the concept I found most intriguing. You can see my thoughts about and explanation of the fast time vs. slow time concept here.
Over the last few weeks, I’ve been thinking about this concept from an investor’s perspective more. I went back and read notes and highlights from books about super investors. My takeaway so far is that the investors who’ve generated outsize returns essentially used slow time, fast time as a core part of their investment evaluation.
While everyone else focused on the current state, these investors waited until the current state wasn’t sustainable (i.e., an asset price was extremely appreciated or depressed). They thought about what the likely future state would look like (without being able to predict when) based on their own analysis of that asset’s prospects. They acted decisively based on the future state they believed had a high probability of becoming reality. While everyone else was positioned for the present to continue, they positioned themselves for the future. This often meant that their actions were the opposite of everyone else’s, which sometimes exposed them to criticism. But once they’d made their move, they sat back and waited for the future they’d predicted to arrive. For weeks, months, or even years. If their predictions were right, when they finally started to play out, they did so rapidly, and the investors realized outsize returns.
I’m still thinking this concept through, but those are some of my current thoughts.
How Much Profit Do the Lakers Really Make?
Today I read an article (see here) that detailed the Los Angeles Lakers’ expected revenue, expenses, and profits. I’ve been interested in the team since reading a Jack Kent Cooke biography (see here) describing how he bought the team for $5.17 million in 1965 and sold it, along with the NHL Kings and other assets, to Jerry Buss (whose family are the current owners) for $67 million in 1979 (see here). I’ve been following the story about last month’s offer to acquire the team for $12.5 billion and am curious about the numbers supporting that valuation.
So, here are the 2026 financial projections the article shared (they’re pulled from an investor deck that Thrive Capital is using to raise money from investors):
- Total revenue: $681 million
- Total expenses: $552 million
- EBITDA (i.e., profit): $129 million
Here are a few things I found interesting:
- Players and coaches: $251 million expense
- NBA assessment: $96 million expense
- Tickets and game-day sales: $245 million revenue
- Local media rights: $180 million revenue
- National media rights: $144 million revenue
- Sponsorships: $80 million revenue
So, in round numbers, the cost of players and coaches is 37% of revenue, and that huge dollar amount is spread across a small number of people (I assume, since the player roster is about 15 people). And total media revenue ($324 million) is 48% of total revenue ($681 million). The Lakers’ game-day and ticket sales are huge at 36% of revenue, which I wasn’t expecting.
I’m not sure how the group buying the Lakers came up with the $12.5 billion valuation, but it’s interesting to see the business numbers. Given these numbers, I’d imagine there are lots of other factors and assets, beyond the EBITDA, that contribute to the deal price.
SpaceX Wants Failed Startups’ Data. Why?
Today I read a Bloomberg article (see here) that reported that SpaceX had discussed buying customer and operational data from struggling or failed start-ups. This is the second time I’ve seen a notable company consider buying or make an offer for data from struggling companies: A few months ago, Google offered $10 million for Spirit Airlines’ data after the company filed for bankruptcy.
In the world of AI, especially physical AI, it’s becoming clear that the right kind of data is valuable because it can be used to train AI. The SpaceX and Google moves confirm that companies, some struggling and left for dead, could be sitting on valuable and ignored assets. For public companies, this is more interesting because that data likely doesn’t show up as a balance-sheet asset.
I think private-market investors are ahead of the curve on this right now. But when public-market investors start thinking about this more and quantify the value of the data that some (not all) public companies have, that could have a material impact on the valuation of the few companies that have large, unique, proprietary data sets.
How to Get Ahead: Slow Time vs. Fast Time
Two weeks ago, I read How to Get Rich in American History. It’s a history book that describes the strategies Americans used to create wealth and improve their financial position over 300 years. One concept that got me thinking was from Chapter 2, “Fast Time, Slow Time.”
Roughly, the idea is that fast time and slow time are just what they sound like. During slow time, life moves at a steady pace. Change happens slowly, making it easy to digest. Fast time is the opposite: Life, or aspects of life, move rapidly. Change happens at lightning speed.
The author of the book applies this idea to the accumulation of wealth: Slow time is following a steady approach to accumulating wealth. Think of working for the same company, learning a skill, and saving money for a decade or two. Fast time is taking an accelerated approach to accumulating wealth. Think of opening a business at the right time, when demand from potential customers is high, and the business producing a life-changing profit for the owners after one or two years.
This got me thinking about things that affect change and the rate of change.
A major factor is that change is sometimes random. Life is unpredictable, and you should expect some curveballs. Who had a global pandemic on their radar in January 2020?
When the rate of change and randomness are at normal levels, we’re in slow time. The change that we experience doesn’t feel like it alters life much. It feels manageable. Think 2019.
When the rate of change and randomness are elevated, we’re in fast time. The change feels extraordinary or life-altering. Adapting to this level of change can be difficult. Think 2020 and COVID-19.
Life isn't stable; it can change suddenly. You have to expect both slow change and rapid, surprising change. This being the case, how have people leveraged both slow time and fast time to accelerate their progress?
The author made a great point:
Those who can live in the present while building in the expectation for change —even if they aren’t always sure just how or when it’s coming—have a leg up on those who presume the brave new world of tomorrow will actually arrive tomorrow (or, on the flip side, never).
My take is that many people who realize outsize gains during fast time do so because they positioned themselves well during slow time. They planned for change and took steps during slow time that would give them an advantage when (or if) change occurs.
In the book, Norman McGhee is a great example. For 10 or 15 years, he studied business from the bottom up, despite racial headwinds. By his mid-thirties he was worth very little, but he understood business. When the Great Depression hit (fast time), many people lost their homes. McGhee, leveraging his knowledge of business, bought 100 foreclosed homes, which he turned into rentals. He borrowed 100% of his costs and banked on the homes’ values rising. McGhee knew a business opportunity would present itself to him one day, and he wanted to be prepared to act decisively when it did. This investment helped McGhee become one of the most prominent black businessmen of his era. His success in real estate allowed him to break the racial barrier on Wall Street and become one of the first black stockbrokers.
Change often begins slowly and then takes off, seemingly all at once. During slow time, spotting that change or at least understanding that the future will look different than the present in unanticipated ways is key. If you can do this, you can plant seeds during slow time that will produce an excellent harvest during fast time, when rapid change occurs.
7 Wealth Strategies That Survived 300 Years
A few weeks ago, I came across a podcast in which a history professor turned real estate investor shared what he’d learned from researching 300 years of Americans climbing the economic ladder. He spent over 10 years reading history and trying some of the strategies himself. He shared everything in his book, How to Get Rich in American History, which I read last week.
There are lots of good takeaways in this book. One of them is that most financial advice we think is timeless hasn’t held throughout history. Today I’ll share the seven strategies that Americans used throughout history to get ahead:
- Built their own business
- Took a large income in someone else’s business
- Combined several small incomes to create excess income
- Invested extreme portions of their income
- Leveraged a high-payout opportunity with debt or risk
- Invested steadily over a long period of time
- Married well
Number 6 is valid, but timing matters because the stock market has had terrible periods. So, as much as timing the market is frowned upon now, history says you should time it when you use strategy #6.
These strategies are pretty straightforward. Using a combination of them intelligently is how people got ahead in life over the last 300 years.
Price Is Not Value
I caught up with a friend this past week. He’s considering making an investment. He shared his thinking and asked me if I thought it was a good investment.
I told him I had no idea. Partly this was because I’m unfamiliar with the asset class, but more fundamentally it was because he said nothing about what he thinks the asset is worth today. I heard only about the price the seller wants.
Investing, in my opinion, is all about buying something for less than it’s worth. An important distinction is between price and value. Price is what you pay for the asset. Value is what you get. If you pay more than the asset is worth, it’s not such a great investment. To be a good investor, you have to be able to use your judgment to determine an asset’s value. There are lots of ways to do that. But if your analysis is thorough and you buy for less than value…you have a good chance of making a good investment.
LeBron James: The $300M Bond King?
Ever since I read Dangerous Dreamers last year and learned about the insight that led to Michael Milken creating a high-yield bond market, I’ve been curious about bonds. Wanting to understand this asset class better, I’ve bought several books, including a biography of Bill Gross by Mary Childs, The Bond King.
Today I learned more about bonds from an unexpected person: LeBron James. Bloomberg reported that James used a sophisticated strategy to borrow several hundred million dollars. LeBron has made almost $600 million in NBA salary (source), and he also has other revenue streams, including sponsorships by Nike and other companies.
James’s income from those non-NBA sources runs through his company, King James Funding LLC. In 2018, to get cash up front, King James LLC issued ~31-year bonds. Those bonds paid an interest rate of 4.8% and aren’t due until 2049. The total bond purchase by investors was reported to be almost $300 million; it isn’t clear whether that was the total amount sold over several years or the initial amount sold in 2018.
So why did this catch my eye? LeBron James basically borrowed several hundred million dollars backed by his future non-basketball earnings (and likely some assets too). He accomplished this by having his personal company issue bonds that were bought by insurance companies.
I think it’s an interesting case of a private company using future revenue streams to raise immediate capital. I’ve been thinking about bonds in relation to public companies, but this has me thinking about them in relation to private companies too. I definitely want to learn more about LeBron’s deal structure. Hopefully I can find public filings that shed more light on the bonds he issued.